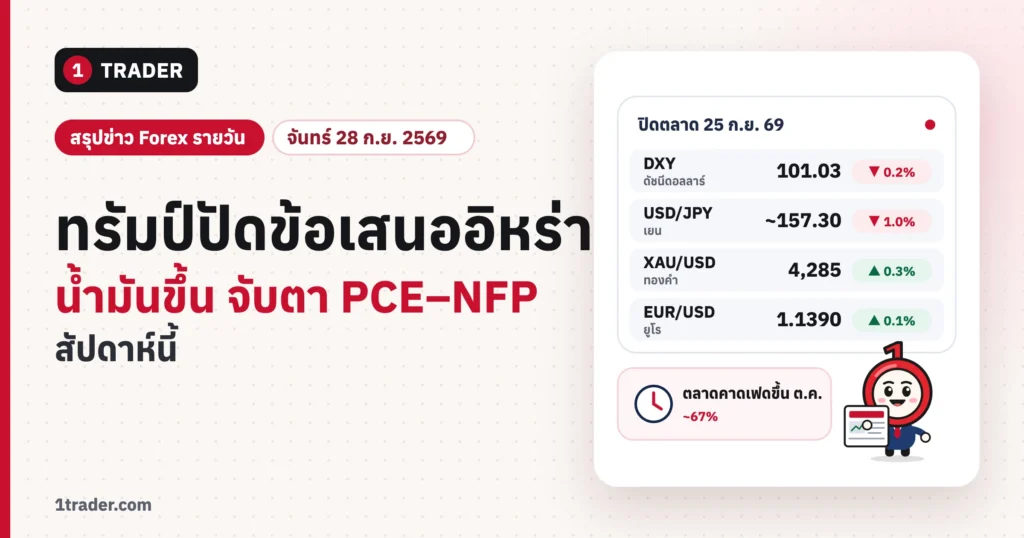
Trump rejected Iran’s offer to reopen the Strait of Hormuz, so oil edged higher at the Monday open. The dollar ended last week up for a second straight week, while gold eased back to around $4,250. This week markets await PCE and Nonfarm Payrolls, which will signal whether the Fed hikes rates in October.
Updated Mon 28 Sep 2026 · 00:54 GMT · Prices in this article as of the New York close on Fri 25 Sep 2026 (gold and oil prices early on 28 Sep are timed in the text)
Key takeaways
- 1Trump rejected Iran’s offer to reopen the Strait of Hormuz within 7 days, but said he expects talks to resume this week. WTI crude edged higher on Monday morning
- 2The dollar (DXY) closed Friday around 101.03, slightly lower, but still up about 0.8% on the week. The 10-year yield closed around 5.18%
- 3Gold ended the week at $4,285, down 2.2%, and eased to around $4,250 on Monday morning, near a 7-week low
- 4A packed week: RBA (Tue 04:30 GMT), PCE (Wed 30 Sep), ISM (Thu 1 Oct) and Nonfarm Payrolls (Fri 2 Oct)
Key events Mon 28 Sep 2026
- Dallas Fed manufacturing (Sep)Texas factory activity indexMED
- Barkin (Richmond Fed) speaksWatch for his stance on an October hikeMED
- Lagarde and Elderson (ECB) speakAlso BoE’s RamsdenMED
- RBA decisionCurrent rate 4.35% · market expects a hike to 4.60% (tomorrow)HIGH
Market overview
Approximate closing prices as of Friday 25 Sep 2026 (New York close) · ▲▼ = daily change · 7W = 7-week low
Overnight market recap
Markets opened the week cautiously after President Trump rejected Iran’s offer to reopen the Strait of Hormuz within 7 days, which was conditional on lifting the naval blockade and unfreezing assets. Iran insisted it would not soften its terms, while Trump said he expects talks to resume this week and on Sunday did not rule out further strikes. WTI crude, which closed Friday around $92.41 (down 2.3%), therefore edged higher on Monday morning (28 Sep). The Trump–Xi summit on 23–27 Sep only produced an extension of the trade truce to 10 Jan 2027.
On the data front on Friday (25 Sep), August durable goods orders were flat at 0.0%, better than the expected 0.4% decline, but orders ex-transportation rose 0.3%, less than forecast. The final September UMich consumer sentiment index came in at 48.1, a 4-month low, with 1-year inflation expectations at 4.6%, the highest since June, and long-run expectations at 3.4%. The dollar slipped slightly on Friday but still posted a second weekly gain. Markets still price about a 67% chance that the Fed will raise rates from 3.75–4.00% in October, keeping the 10-year yield around 5.2%.
“Gold needs to get back above $4,400 before it counts as a meaningful recovery.”
Marc Chandler (Bannockburn Global Forex) via Kitco, 25 Sep (paraphrased)
Asset by asset
Euro bounces slightly to around 1.1390 but stays near multi-month lows
The euro closed Friday (25 Sep) around 1.1390, slightly higher as the dollar eased, and opened Monday morning around 1.1388. It is still down about 0.8% on the week, and the rate differential from a possible further Fed hike continues to weigh on the pair. Today Lagarde speaks, and late in the week comes flash eurozone inflation (2 Oct), which will signal whether the ECB keeps hiking.
Yen recovers to around 157.30 after Japan says Trump is concerned about the weak yen
The yen strengthened on Friday (25 Sep), snapping a 5-day losing streak, after Japanese Finance Minister Satsuki Katayama said Trump expressed concern about the weak yen in talks with Prime Minister Takaichi. USD/JPY closed around 157.30 and opened Monday morning around 157.25, but the still-wide rate differential limits the yen’s recovery. This week brings the Tankan survey (1 Oct) and Tokyo CPI (2 Oct).
Gold ends the week down 2.2% and eases to around $4,250 on Monday morning
Gold closed Friday (25 Sep) at $4,284.97, up 0.26% on the day but down 2.17% for the week according to Kitco, with a weekly low of $4,244.63. On Monday morning (28 Sep) prices eased to around $4,250 according to Trading Economics, near a 7-week low, as yields stay high and markets still expect a Fed hike.
What to watch today
There is no high-impact US data on Monday 28 Sep, only the Dallas Fed manufacturing index at 14:30 GMT and a speech by Richmond Fed President Thomas Barkin at 16:30 GMT, so markets are likely to trade mainly on Iran headlines and oil prices. Tomorrow (29 Sep) at 04:30 GMT the Reserve Bank of Australia (RBA) announces its rate decision and is expected to hike from 4.35% to 4.60%. The big US releases this week are JOLTS (29 Sep), August PCE prices (30 Sep, 12:30 GMT), ISM manufacturing (1 Oct) and September Nonfarm Payrolls (2 Oct). See last week’s recap in the Weekly Forex Recap and the latest rate table on the central bank rates page.
Our view
The main theme is still further Fed hikes and high oil prices from the US–Iran conflict, so the dollar still has the edge. But with no key data today, prices may swing mainly on negotiation headlines. The real deciders are PCE on Wednesday and Nonfarm Payrolls on Friday.
- 1Watch Iran headlinesNews of talks or strikes could swing oil and gold sharply
- 2Size down before big dataPCE (30 Sep) and NFP (2 Oct) could change the dollar’s direction
- 3Use a stop-loss on every tradeEspecially AUD/USD around tomorrow’s RBA decision at 04:30 GMT
Big PCE–NFP week: cut your cost on every lot with rebates
Rebate per lot · Standard Plus account
Rebate per lot · Standard account
Rebate per lot
1TRADER is a partner (IB) of these brokers and earns a commission when you open an account through our links · % is the share of the IB commission returned to you, not a percentage of your deposit · Rates as of Sep 2026 · Compare rebates across brokers
Learn to trade free with 1TRADER
Sources (16)
- U.S. Census – Durable Goods, Aug (25 Sep)
- University of Michigan – Surveys of Consumers, Sep (25 Sep)
- BEA – PCE/GDP release schedule (30 Sep)
- TradingView – DXY / EUR/USD
- Trading Economics – DXY / FedWatch (25 Sep)
- Trading Economics – JPY
- Trading Economics – GBP
- Trading Economics – AUD / RBA
- Trading Economics – Gold (28 Sep)
- Kitco – Gold weekly (25 Sep)
- Investrade – Market Review 25 Sep
- investingLive – Monday open prices 28 Sep
- FXStreet – Iran/Hormuz (27 Sep)
- FXStreet – Trump/oil (28 Sep)
- FXStreet – Trump–Xi summit
- Investing.com – Calendar 28 Sep
Risk warning: Trading forex, gold and CFDs carries a high level of risk and you may lose all of your capital. This news summary is for educational purposes only and is not investment advice. Prices in this article may have changed by the time you read it.
Compiled by the 1TRADER editorial teamEditorial policy and sourcesFull risk disclosureReport an error
Read more
Related news
 Forex NewsThai Baht Today 5 Oct 2026open 33.55–33.56 steady NFP weak, but foreigners still selling Thai stocks
 Forex NewsWeekly Forex Recap 28 Sep–2 Oct 2026: NFP Misses, Dollar Up, Gold −3%
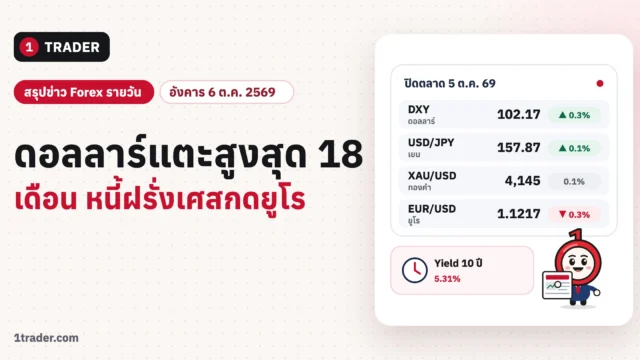 Forex NewsForex News 6 Oct 2026: Dollar at 18-Month High, French Debt Weighs on Euro
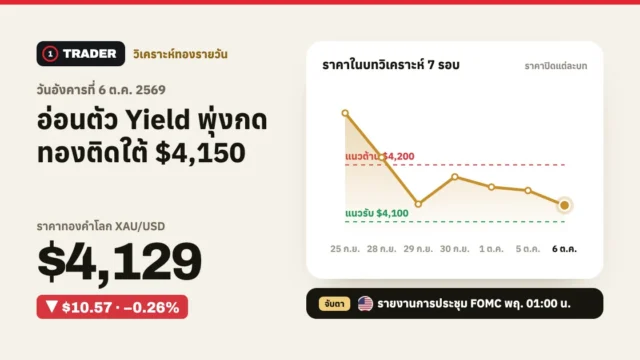 Forex NewsGold Price Today 6 Oct 2026: XAUUSD Eases to $4,129 as Yields Surge