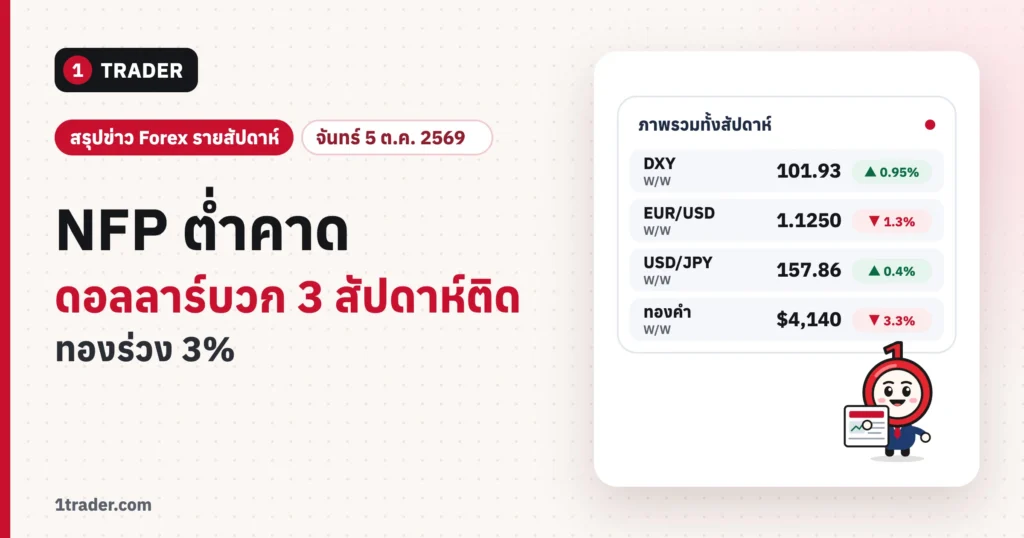
The dollar (DXY) closed higher for a third straight week even though September NFP came in at just 29K, far below forecast. The euro (EUR/USD) fell about 1.3% on French debt worries, world gold (XAUUSD) dropped about 3.3% for a second losing week, and the US 10-year Treasury yield kept climbing to around 5.28%.
Updated Mon 5 Oct 2026 · 04:50 GMT · New York closing prices Fri 2 Oct 2026 vs. the close on Fri 25 Sep 2026
Key takeaways of the week
- 1September NFP rose by only 29K (forecast 90K) and the unemployment rate rose to 4.2%. Markets scaled back bets on a Fed hike on 28 Oct, with the odds of a hold rising to about 72–78% from about 36% a week earlier
- 2DXY hit 102.20 on Thursday, its highest since April 2025, before easing after NFP, but still closed the week up 0.95% while the 10-year yield climbed back to close near 5.28%
- 3The French–German 10-year yield spread widened to its widest since 2011, pushing the euro to its lowest since early 2025, while flash eurozone inflation accelerated to 3.8% on energy prices
- 4Core PCE for August came in at 3.0% y/y, below the 3.3% forecast. The RBA raised rates to 4.60%, and Brent crude held above $100 on Middle East tensions
Weekly performance
Closing prices Fri 2 Oct 2026 (New York) vs. the close on Fri 25 Sep 2026 · Sources: Trading Economics and Investing.com (gold: Investing 4,149 / Trading Economics 4,140 · DXY: ActionForex 101.92) · % rounded and may differ slightly by price source
What happened this week
Early in the week (29 Sep) the RBA raised rates by 0.25% to 4.60% as expected, while August JOLTS job openings held steady at 7.1 million. On Wednesday 30 Sep, Core PCE, the Fed’s preferred inflation gauge, came in at 3.0% y/y, below the 3.3% forecast. The dollar dipped briefly, but the bigger picture was still supported by steadily rising US yields.
The dollar peaked on Thursday 1 Oct when DXY hit 102.20, its highest since April 2025. The main drivers were surging bond yields and worries over French public finances. The French–German 10-year yield spread widened beyond 150bp, the most since the 2011 eurozone debt crisis. The euro slid to around 1.12, its lowest since early 2025, and ended the week down about 1.3%, its biggest weekly drop in months. The same day, the September ISM Manufacturing PMI came in at 54.5, close to the prior month, but the prices-paid index jumped to 77.9.
On Friday 2 Oct, flash eurozone inflation for September accelerated to 3.8% from 3.2%, with energy prices up 18.8% y/y. That evening US NFP came in at just 29K versus the 90K forecast, the unemployment rate rose to 4.2% and wages grew 3.0% y/y, below forecast. DXY broke below 102 to under 101.70 before recovering to close at 101.93, while the 10-year yield climbed back to close near 5.28%, its highest in roughly two decades. As a result, gold did not benefit from the weak jobs data and closed the week near $4,140–4,150, down about 3.3%.
Key data results of the week
- Tue 29 Sep · AustraliaRBA raised rates by 0.25% to 4.60% as expected and signalled it is ready to hike again if needed · See central bank rates →
- Tue 29 Sep · USJOLTS job openings (Aug) 7.1 million steady; July revised up to 7.3 million
- Wed 30 Sep · USHIGHCore PCE (Aug) 3.0% y/y below the 3.3% forecast, and 0.2% m/m · Read the analysis →
- Thu 1 Oct · USISM Manufacturing (Sep) 54.5 from 54.6; prices index jumped to 77.9 · jobless claims 197K, lowest since mid-July
- Fri 2 Oct · EurozoneFlash inflation (Sep) 3.8% from 3.2%; core inflation 2.5% · Read the latest forex news →
- Fri 2 Oct · USHIGHNonfarm Payrolls (Sep) 29K below the 90K forecast, unemployment 4.2%; July–August revised down by a combined 60K · Read the analysis →
Daily gold: Gold price today →
Outlook for next week
The main theme is still whether the Fed will hike again on 28 Oct. After the weak NFP, markets are leaning more toward a hold, but long-term yields remain high and energy-driven inflation is not over. Next week has less US data than this week, starting with ISM Services on Monday, followed by the minutes of the September FOMC meeting at 18:00 GMT on Wednesday, and wrapping up with the preliminary UMich survey on Friday. Markets will watch whether most Fed officials still leave the door open to further hikes. See interest rates and upcoming meeting dates in the central bank rates table
Outside the US, Friday’s Canadian jobs data will move the Canadian dollar ahead of the BoC meeting on 28 Oct, while the euro remains sensitive to French fiscal news and the yield spread with Germany after eurozone inflation accelerated to 3.8%, which will shape the ECB’s direction at its 29 Oct meeting.
Risks to watch: oil prices swinging on Middle East headlines, fast-rising long-term yields that weigh on gold, and USD/JPY still around 158, near the zone where Japan has previously warned about the currency. China’s Golden Week holiday runs until 7 Oct, so liquidity in the Asian session may be thinner. This article is a market overview, not investment advice.
- ISM Services (Sep)Mon 5 Oct · prior 55.4HIGH
- FOMC minutes (15–16 Sep)Wed 7 Oct · the meeting where the Fed raised rates to 3.75–4.00%HIGH
- Canada employment (Sep)Fri 9 Oct · prior unemployment rate 6.4%HIGH
- UMich consumer sentiment, preliminary (Oct)Fri 9 Oct · prior 48.1HIGH
Our view
The dollar is still supported by high yields, but the weak NFP has taken some momentum out of the Fed-hike story. Next week is lighter on news, and the key moment is the FOMC minutes on Wednesday at 18:00 GMT.
- 1Be careful around the FOMC minutesReleased at 18:00 GMT; thin liquidity can make prices gap
- 2Watch yieldsThe 10-year yield near 5.3% is still weighing on gold
- 3Use a stop loss on every tradeMiddle East news is making oil and currencies swing sharply
Dollar up 3 weeks in a row: cut your cost on every lot with rebates
Rebate per lot · Standard Plus account
Rebate per lot · Standard account
Rebate per lot
1TRADER is a Partner (IB) of these brokers and receives a commission when you open an account via our links · % is the share of the IB commission returned to you, not of your deposit · rates as of Sep 2026 · Compare rebates for all brokers
Learn to trade for free with 1TRADER
Sources (15)
- FXStreet – NFP 29K / DXY (2 Oct)
- FXStreet – Forex Today (2 Oct)
- FXStreet – week ahead
- ActionForex – Weekly Report (3 Oct)
- Reuters – euro / France (2 Oct)
- Saxo – Market Quick Take (2 Oct)
- Eurostat – HICP Sep
- BLS – JOLTS
- ISM – Manufacturing Sep
- RBA (29 Sep)
- Trading Economics – gold
- Trading Economics – currencies
- Trading Economics – commodities
- Trading Economics – US10Y
- Investing.com – historical prices
Risk warning: Trading forex, gold and CFDs carries a high level of risk and you may lose all of your capital. This news summary is for educational purposes only and is not investment advice. Prices in this article may have changed by the time you read it.
Compiled by the 1TRADER editorial teamEditorial policy and sourcesFull risk disclosureReport an error
Read more
Related news
 Forex NewsWeekly Forex Recap 12–16 Oct 2026: Dollar Snaps 4-Week Run, Oil Tops $100
 Forex NewsBreaking: Asian Stocks Crash as KOSPI Drops 8%, Nikkei −5%, Gold Rebounds
 Forex NewsForex News 16 Oct 2026: Hot PPI, Yields Fall, Dollar Below 102, Gold +1.5%
 Forex NewsGold Price Today 16 Oct 2026: XAUUSD Steady Near $4,156 Ahead of Warsh