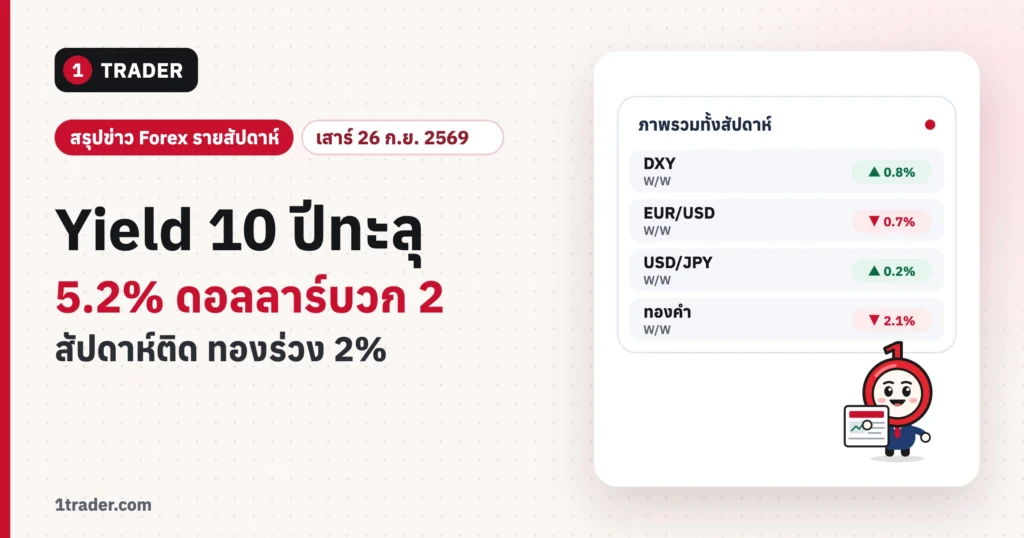
This week the bond market set the direction. The US 10-year Yield jumped above 5.1% after hot PMI data, and several Fed officials backed further rate hikes. The dollar rose for a second straight week and gold fell about 2%, while the yen rebounded on Friday after Japan revealed that Trump was also worried about the weak yen.
Updated Sat 26 Sep 2026 · 02:14 GMT · New York closing prices Fri 25 Sep 2026 vs. close on Fri 18 Sep 2026
Key takeaways of the week
- 1US flash PMI (23 Sep) ran hot, with input costs rising at the fastest pace in 4 years. The 10-year Yield jumped 13bp to 5.10% and ended the week near 5.17%, the highest since 2007
- 2Fed officials Williams, Hammack and Paulson backed more hikes. Markets priced a 66–69% chance of a Fed hike in October (CME FedWatch, 25 Sep)
- 3The dollar (DXY) touched 101.40, a 2-month high, before easing on Friday and ended the week up about 0.8%. Gold fell about 2%, while sterling and the Aussie dollar lost more than 1%
- 4On Friday Japan said Trump was concerned about the weak yen. USD/JPY fell about 1%, while WTI crude lost about 7% on the week on hopes for US–Iran talks
Weekly performance
Approximate closing prices as of Fri 25 Sep 2026 (New York) vs. close on Fri 18 Sep 2026 · Sources: Trading Economics, Investing.com, exchange-rates.org and Reuters · % rounded and may differ slightly by price source
What happened this week
Early in the week (21–22 Sep) markets traded in a range after the Fed hiked rates on 16 Sep and the BoJ raised its rate to 1.25% on 18 Sep. The turning point came on Wednesday 23 Sep, when the US flash PMI came in hot: output grew at the fastest pace in more than 5 years and input costs rose at the fastest pace in 4 years. Bonds sold off hard, and the 10-year Yield jumped about 13bp to 5.10%, the highest since 2007. The dollar strengthened across the board that day, the euro lost about 0.6% and the Aussie dollar fell more than 1%.
On Thursday 24 Sep Fed officials John Williams, Beth Hammack and Anna Paulson all signalled that more hikes may be needed. With initial jobless claims at just 197K, the dollar index climbed to 101.40, a 2-month high, the 10-year Yield rose to around 5.2%, and gold slipped toward $4,200, a 7-week low. The same day the SNB held its rate at 0% as expected.
On Friday 25 Sep the dollar eased somewhat. Japanese Finance Minister Satsuki Katayama revealed that President Trump had voiced concern about the weak yen to Prime Minister Takaichi, and the yen posted its biggest gain in 2 weeks, with USD/JPY down about 1% to around 157.2. WTI crude fell about 2% to $92.41 on news of US–Iran talks, leaving it down about 7% on the week. Even though the dollar was weaker on the last day, it still closed with a second straight weekly gain, the first since June.
Key data results of the week
- Wed 23 Sep · USS&P Global flash PMI (Sep) Output grew at the fastest pace in more than 5 years and costs rose at the fastest pace in 4 years; 10-year Yield +13bp
- Thu 24 Sep · USInitial jobless claims 197K Below the 201K forecast; the labor market is still tight · Read the 25 Sep news recap →
- Thu 24 Sep · SwitzerlandSNB holds rate at 0% As expected · See central bank rates table →
- Fri 25 Sep · USDurable goods orders (Aug) flat at 0.0% Better than the expected decline, while core capital goods orders rose 1.6%
- Fri 25 Sep · USHIGHUMich consumer sentiment (final) 48.1 Above the 47.6 forecast; 1-year inflation expectations steady at 4.6% and 5-year at 3.4% · Read the analysis →
Daily gold: Gold price 25 Sep →
“This bond selloff is not a crisis, but it is a warning sign about inflation”
Rick Rieder, BlackRock, interview with Yahoo Finance, 25 Sep (paraphrased)
Outlook for next week
The main theme is still whether the Fed will hike again in October. A big batch of US data lands in a single week: JOLTS on Tuesday, Core PCE (the Fed’s preferred inflation gauge) on Wednesday, ISM manufacturing on Thursday, and Nonfarm Payrolls on Friday 2 Oct. If the numbers stay strong, Yields and the dollar could get more support, but if the labor market starts to slow, we may see profit-taking after the dollar’s 2-week rally.
Outside the US, the RBA announces its rate decision on Tuesday 29 Sep, with markets expecting a 0.25% hike to 4.60%. Eurozone flash inflation on Friday is expected to accelerate to about 3.5% from 3.2%, which will shape the ECB outlook. See current rates and next meeting dates in the central bank rates table
Risks to watch: USD/JPY near the 160 zone where Japan may intervene, US–Iran talk headlines that make oil swing sharply, and fast-rising long-term Yields. China is on its Golden Week holiday 1–7 Oct, so liquidity during the Asian session may be thinner. This article is a market summary, not investment advice.
- RBA rate decisionTue 29 Sep · currently 4.35%, expected hike to 4.60%HIGH
- JOLTS job openings (Aug)Tue 29 Sep · previous 7.27 millionHIGH
- Core PCE (Aug)Wed 30 Sep · previous 3.3% y/yHIGH
- ISM manufacturing (Sep)Thu 1 Oct · previous 54.6HIGH
- Eurozone flash HICP inflation (Sep)Fri 2 Oct · previous 3.2% y/yHIGH
- Nonfarm Payrolls (Sep)Fri 2 Oct · previous +162K, unemployment 4.1%HIGH
Our view
The dollar still has the edge from high Yields and the Fed’s stance, but next week has major news almost every day, so prices could swing sharply both ways, especially on Wednesday (Core PCE) and Friday (NFP).
- 1Reduce position size around newsOn PCE and NFP releases, spreads may widen and prices may gap
- 2Watch the yenUSD/JPY near 160 risks intervention
- 3Set an SL on every orderGold remains volatile with Yields
In volatile markets like this, cut your cost on every lot with rebates
Rebate per lot · Standard Plus account
Rebate per lot · Standard account
Rebate per lot
1TRADER is a Partner (IB) of these brokers and earns commission when you open an account through our links · % is the share of IB commission returned to you, not of your deposit · Rates as of Sep 2026 · Compare rebates across all brokers
Learn to trade for free with 1TRADER
Sources (15)
- Reuters – Dollar set for weekly gain; yen rallies (25 Sep)
- FXStreet – Forex Today (25 Sep)
- FXStreet – EUR / UMich / FedWatch (25 Sep)
- FXStreet – Week ahead
- Wolf Street – PMI / Yield (23 Sep)
- ActionForex – Yen / RBA
- SNB (24 Sep)
- The National – Oil
- Market close 25 Sep
- Yahoo Finance (25 Sep)
- Trading Economics – DXY
- Trading Economics – Gold
- Trading Economics – US10Y
- Investing.com – Historical prices
- exchange-rates.org
Risk warning: Trading Forex, gold and CFDs carries a high level of risk and you may lose all of your capital. This news is a summary for educational purposes, not investment advice. Prices in this article may have changed by the time you read it.
Compiled by the 1TRADER editorial teamEditorial and sourcing policyFull risk disclosure
Read more
Related news
 Forex NewsGold Price Today 1 Oct 2026: XAUUSD Steady Near $4,160 After Soft PCE
 Forex NewsThai Baht Today 1 Oct 2026open 33.60–33.61 steady foreigners sell Thai stocks ahead of ISM tonight
 Forex NewsWeekly Forex Recap 28 Sep–2 Oct 2026: NFP Misses, Dollar Up, Gold −3%
 Forex NewsUS NFP Sep 2026 Comes In at 29K, Far Below 90K Forecast; Jobless 4.2%