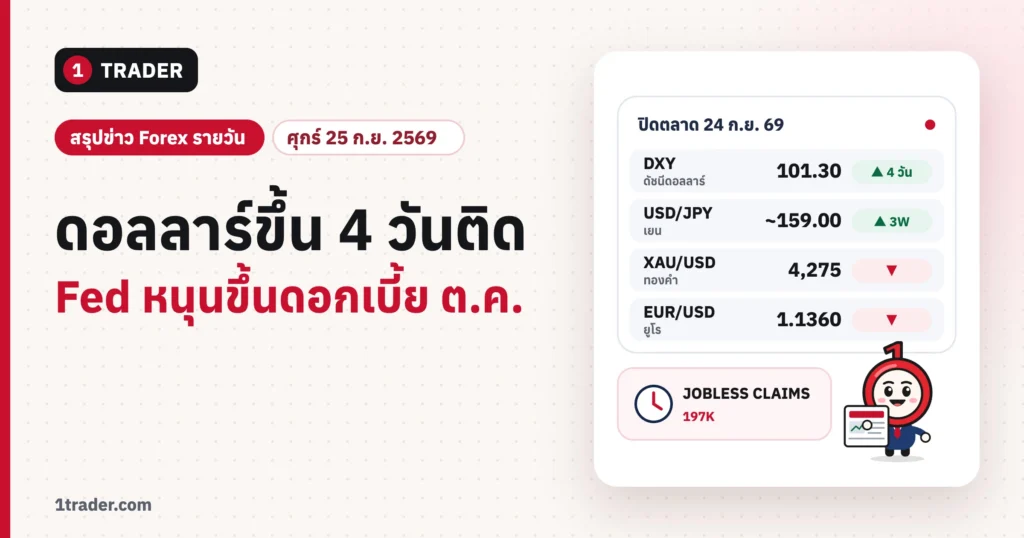
Three Fed officials came out in favour of further rate hikes, sending the dollar higher for a fourth straight day. The 10-year yield climbed above 5.2%, the euro and sterling fell to multi-month lows, and gold slipped below $4,300.
Updated Fri 25 Sep 2026 · 02:50 GMT · Prices in this article as of the New York close on 24 Sep 2026 (gold, yields and EUR/USD as of the Asian session on 25 Sep)
Key points
- 1Three Fed officials (Williams, Hammack, Paulson) backed further rate hikes; markets price a 67.5% chance of an October hike
- 2The dollar (DXY) touched 101.40, its highest since late July, rising for a fourth straight day; the 10-year yield is near 5.22%
- 3The euro is around 1.1360–1.1375, sterling is testing 1.3200 and the yen weakened toward 159.00 despite a warning from Japan’s finance minister
- 4Today, watch Durable Goods (12:30 GMT), UMich (14:00 GMT) and three more Fed speakers
Today’s events · Fri 25 Sep 2026
- Durable Goods (Aug)Forecast −0.4% (previous +1.1%)MED
- HIGH
- Fed speakersWilliams, Schmid, HammackHIGH
Market overview
Approximate closing prices on Thursday 24 Sep 2026 (New York) · 3M/2M/3W = 3-month / 2-month / 3-week high or low
Overnight market recap
The US dollar rose for a fourth straight day on Thursday (24 Sep), with the dollar index (DXY) touching 101.40, its highest since late July, before closing around 101.30. The main driver was three Fed officials who all signalled that more rate hikes may be needed. New York Fed President John Williams said one more hike this year is to be expected, Cleveland Fed President Beth Hammack warned that inflation risks remain tilted to the upside, and Philadelphia Fed President Anna Paulson said further gradual hikes may be needed if the economy evolves as expected.
Economic data supported the theme. The US Labor Department reported initial jobless claims for the week ending 19 Sep at 197K, below the 201K expected, and August new home sales rose 6.4%. According to CME FedWatch on Friday morning (25 Sep), markets put the odds of a 0.25% Fed hike in October at 67.5%, up from 55.4% a week earlier. The US 10-year Treasury yield rose to around 5.22%, its highest since 2007, and the 30-year yield to around 5.50%, its highest since 2004. Oil eased on Friday morning after reports that the US and Iran may hold talks on the Strait of Hormuz.
“The dollar rally is starting to look stretched”
ING strategists, 24 Sep (paraphrased)
Asset by asset
Euro steadies near 1.1375, close to multi-week lows
The euro closed Thursday around 1.1360 and traded near 1.1375 on Friday morning (25 Sep). Germany’s IFO index improved to 89.9, but the widening rate gap between the US and Europe continues to weigh on the euro. As long as markets believe the Fed will hike in October, rebounds in EUR/USD tend to be sold. Today, watch comments from the ECB’s Boris Vujčić and the US data later in the day.
Yen weakens toward 159.00 as Japan warns but holds fire
USD/JPY rose for a fifth straight day to near 159.00, a 3-week high. Japanese Finance Minister Satsuki Katayama reiterated that the principles of the 31 Jul joint intervention with the US still apply, but did not name a price level. The BoJ raised rates to 1.25% on 18 Sep, yet the still-wide yield gap has pushed the pair toward 160, a zone where intervention risk rises.
Gold bounces to around $4,290 but still risks a weekly loss
Gold fell to a 7-week low near $4,200 on Thursday (24 Sep) and closed around $4,275 before bouncing about 0.4% to around $4,290 on Friday morning (25 Sep), according to Trading Economics. However, high yields and a strong dollar make non-yielding gold less attractive, and it remains on track for a weekly loss of more than 2%. Read the full gold analysis →
What to watch today
On Friday 25 Sep the US releases durable goods orders for August at 12:30 GMT, expected to fall 0.4% after a 1.1% rise the previous month, followed by the final UMich consumer sentiment reading at 14:00 GMT. The figure to watch is 1-year inflation expectations, which stood at 4.6% in the preliminary reading; a further rise would strengthen the case for an October hike. Fed officials Williams, Schmid and Hammack are also due to speak again. Next week brings Japan’s Tankan survey (30 Sep) and US nonfarm payrolls (2 Oct).
Our view
The main theme is still further Fed hikes, which favours the dollar. But this rally has run for four straight days and some analysts see it as stretched. If today’s data come in weak or Fed speakers sound softer, we could see profit-taking before the weekly close.
- 1Trade with the trendThe dollar is still in an uptrend; don’t rush to fade it
- 2Watch the weekly closePrices may swing sharply on Friday between 12:30 and 14:00 GMT
- 3Use a stop-loss on every orderEspecially on USD/JPY near the 160 intervention zone
In volatile markets like this, cut the cost of every lot with rebates
Rebate per lot · Standard Plus account
Rebate per lot · Standard account
Rebate per lot
1TRADER is a partner (IB) of these brokers and earns a commission when you open an account through our links · % is the share of the IB commission returned to you, not a percentage of your deposit · Rates as of Sep 2026 · Compare rebates across brokers
Learn to trade free with 1TRADER
Sources (9)
Risk warning: Trading forex, gold and CFDs carries a high level of risk and you may lose all of your capital. This news summary is for educational purposes only and is not investment advice. Prices may have changed by the time you read it.
Compiled by the 1TRADER editorial teamEditorial policy and sourcesFull risk disclosureReport an error
Read more
Related news
 Forex NewsForex News 1 Oct 2026: Soft PCE, but Yields Climb Ahead of ISM
 Forex NewsGold Price Today 1 Oct 2026: XAUUSD Steady Near $4,160 After Soft PCE
 Forex NewsThai Baht Today 1 Oct 2026open 33.60–33.61 steady foreigners sell Thai stocks ahead of ISM tonight
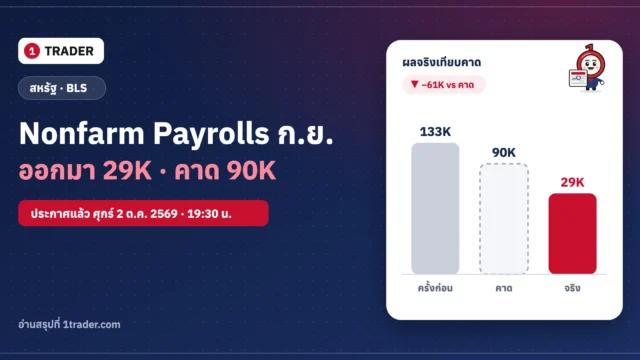 Forex NewsUS NFP Sep 2026 Comes In at 29K, Far Below 90K Forecast; Jobless 4.2%