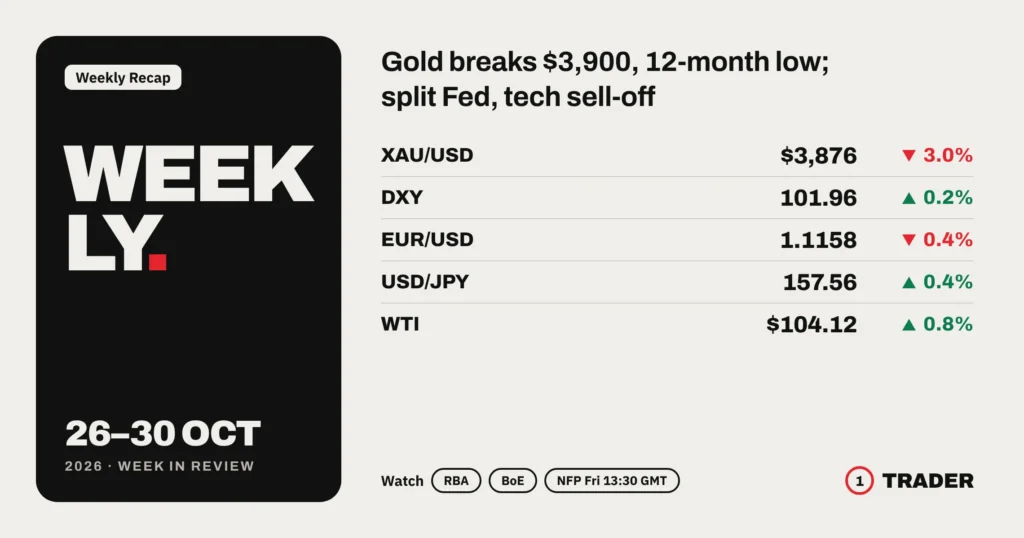
Spot gold (XAUUSD) fell about 3% to close the week near $3,876, its lowest in roughly 12 months, after the Fed held rates in a split 10–2 vote and strong PCE and GDP data lifted bets on a December hike. The dollar (DXY) gained about 0.2% to around 101.96, the euro (EUR/USD) weakened to near 1.116, and crude oil held above $104 after a tanker was attacked in the Strait of Hormuz.
Updated Sat 31 Oct 2026 · 03:24 GMT · New York close on Fri 30 Oct 2026 vs. the close on Fri 23 Oct 2026
Key takeaways of the week
- 1The Fed held rates at 3.75–4.00% as expected, but the vote was 10–2, with Cook and Hammack wanting an immediate 0.25% hike. Markets price a December hike at about 72–75% (CME FedWatch)
- 2September Core PCE came in at 3.1% y/y, in line with forecasts, headline PCE at 3.6%, and Q3 GDP grew 3.4%, beating expectations, supporting the view that inflation is not yet beaten
- 3Gold fell about 3% on the week, dropping more than 3% on Friday alone to break below $3,900 amid a tech sell-off after disappointing earnings (Nasdaq −2.86%), while the 10-year Treasury yield eased to around 4.93%
- 4Other central banks: BoC hiked to 2.50% · RBNZ surprised by holding at 2.75% · ECB held at 2.50% · BoJ held at 1.25% in an 8–1 vote · Brent closed at $117.64, its highest since late April
Weekly performance
Closing prices Fri 30 Oct 2026 (New York) vs. the close on Fri 23 Oct 2026 · FX and DXY from Trading Economics, cross-checked with Investrade (EUR/USD 1.1168 · USD/JPY 157.53) and Convera · Gold: Trading Economics $3,875.84 / December gold futures closed at $3,898.90, down about 2.9% on the week (Investrade) · WTI December contract closed at $104.12 (Investrade, Rio Times) · US10Y: Trading Economics 4.93% / Investrade 4.928% · % figures are rounded and may differ slightly by price source
What happened this week
The week opened with volatility abroad: the Brazilian real slumped after the election result on Monday 26 Oct, while gold tried to hold around $4,000 ahead of the central bank meetings. Wednesday 28 Oct brought several decisions, starting with the RBNZ, which held at 2.75% against market expectations of a hike, sending the New Zealand dollar sharply lower. The BoC then raised rates by 0.25% to 2.50%, its first move after 7 straight holds. Australian September inflation accelerated to 4.3% y/y, keeping the Aussie dollar (AUD/USD) above 0.70
Late on Wednesday 28 Oct the Fed held rates at 3.75–4.00%, but two officials wanted an immediate hike. On Thursday 29 Oct, US Q3 GDP grew 3.4%, beating forecasts, September Core PCE came in at 3.1% as expected and headline PCE accelerated to 3.6%, so markets priced the chance of a December Fed hike at about 72–75%. The ECB held its deposit rate at 2.50% without committing to a future path, and the euro (EUR/USD) slid to 1.1105, its lowest in about 18 months, before recovering partly
On Friday 30 Oct the BoJ held at 1.25% in an 8–1 vote and said underlying inflation is nearing its 2% target. Later in the day US tech stocks were sold off after disappointing results from major companies, with the Nasdaq down 2.86%. Money flowed into bonds, pushing the 10-year yield down to around 4.93%, its lowest in about 7 weeks, yet gold was sold alongside stocks, falling more than 3% through $3,900 to close near $3,876. Meanwhile, an oil tanker was hit by an explosion in the Strait of Hormuz, lifting Brent to a $117.64 close and WTI to $104.12
Key data and decisions this week
- Wed 28 Oct · New ZealandHIGHRBNZ holds at 2.75%, a surprise 4–3 vote vs. an expected hike to 3.00%; the New Zealand dollar fell about 1.4% on the day
- Wed 28 Oct · AustraliaHIGHCPI (Sep) 4.3% y/y up from 4.0%, raising the odds of an RBA hike on 3 Nov
- Wed 28 Oct · CanadaHIGHBoC hikes 0.25% to 2.50% first hike after 7 straight holds · See central bank rates →
- Wed 28 Oct · United StatesHIGHFOMC holds at 3.75–4.00%, 10–2 vote Cook and Hammack wanted a 0.25% hike · Read the analysis →
- Thu 29 Oct · United StatesHIGHCore PCE (Sep) 3.1% · Q3 GDP 3.4% headline PCE 3.6% y/y, GDP beat forecasts · Read the analysis →
- Thu 29 Oct · EurozoneHIGHECB holds deposit rate at 2.50% no commitment on the future path · Read the analysis →
- Fri 30 Oct · JapanHIGHBoJ holds at 1.25%, 8–1 vote Takata proposed a hike to 1.50% · Read the analysis →
Daily gold: Gold Price Today 30 Oct → · Daily news: Forex news →
Week ahead
Next week (2–6 Nov) the main theme remains whether the Fed will hike in December. The key release is October Nonfarm Payrolls on Friday at 13:30 GMT; the previous print was just 29K, the market expects about 56K and unemployment at 4.2%. Before that come ISM manufacturing on Monday and ISM services on Wednesday, both at 15:00 GMT. Tuesday 3 Nov brings the US midterm elections, which could move the dollar and yields through the fiscal outlook. All times GMT
Outside the US, the RBA decides on Tuesday at 03:30 GMT, with markets expecting a hike from 4.60% to 4.85% after Australian inflation accelerated. The BoE announces on Thursday at 12:00 GMT, expected to hike from 3.75% to 4.00%, and Wednesday brings flash eurozone inflation for October, forecast at 3.9%. See the latest rates and next meeting dates in our central bank rates table
Risks to watch: gold has broken below $3,900; if US data stays strong and yields climb again, the pressure may continue, but if the tech sell-off stops, buyers may return. Oil keeps swinging on Strait of Hormuz headlines. US daylight saving time ends on 1 Nov, so 8:30 ET releases will land at 13:30 GMT from next week. This article is a market overview, not investment advice
- US ISM Manufacturing (Oct)Mon 2 Nov · prev. 54.5HIGH
- RBA rate decisionTue 3 Nov · current 4.60%, hike expectedHIGH
- Eurozone flash inflation (Oct)Wed 4 Nov · prev. 3.8%HIGH
- BoE rate decisionThu 5 Nov · current 3.75%, hike expectedHIGH
- US Nonfarm Payrolls (Oct)Fri 6 Nov · prev. 29K, unemployment 4.2%HIGH
Our view
Markets head into next week with gold under pressure, as the Fed keeps the door open to a hike and oil stays expensive, while tech stocks remain volatile. Key events are spread across the week: the RBA, the BoE, Nonfarm Payrolls and the US midterm elections.
- 1US release times shiftFrom 2 Nov, 8:30 ET releases come out at 13:30 GMT
- 2Watch gold at $3,900If it fails to reclaim it, selling may continue into NFP
- 3Use a stop loss on every tradeStrait of Hormuz headlines are causing big swings in oil and gold
Gold breaks $3,900 in a central bank week: get cash back on every lot
Rebate per lot · Standard Plus account
Rebate per lot · Standard account
Rebate per lot
1TRADER is a partner (IB) of these brokers and earns a commission when you open an account through our links · % is the share of the IB commission returned to you, not a percentage of your deposit · Rates as of Sep 2026 · Compare rebates across brokers
Learn to trade free with 1TRADER
Sources (14)
- Trading Economics – Gold (30 Oct)
- Trading Economics – Dollar and currencies
- Trading Economics – US10Y
- Trading Economics – AUD/USD
- Trading Economics – USD/JPY and BoJ
- Investrade – Market Review (30 Oct)
- Rio Times – Oil and the Strait of Hormuz (30 Oct)
- Rio Times – Gold (30 Oct)
- TradingKey – Gold falls below $3,900
- Convera – Weekly FX Report (30 Oct)
- Westpac – RBNZ October Review
- Rio Times – BoC 28 Oct
- ABS – Australia CPI, Sep
- ActionForex – Calendar 2–6 Nov
Risk warning: Trading forex, gold and CFDs carries a high level of risk and you may lose all of your capital. This news summary is for educational purposes only and is not investment advice. Prices in this article may have changed by the time you read it.
Compiled by the 1TRADER editorial teamEditorial policy and sourcesFull risk disclosureReport an error
Read more
Related news
 Forex NewsForex News 29 Oct 2026: Fed Holds in Split Vote, PCE and ECB Up Next
 Forex NewsWeekly Forex Recap 19–23 Oct 2026Gold drops 4% to $4,000, oil surges ahead of central bank week
 GoldGold Price Today 28 Oct 2026: XAUUSD Near $4,048, Steady Before Fed
 Forex NewsBreaking news: Asian stocks crash, KOSPI −8% triggers circuit breaker, Nikkei −5%, gold rebounds