Weekly Forex recap 2–6 Nov 2026: gold (XAUUSD) jumped about 5% in a week when Democrats won the US midterms and took control of both chambers of Congress. WTI crude slid almost 13% on hopes for Iran talks, tech stocks were hit by heavy selling, and the dollar (DXY) turned to a small weekly gain after October NFP came in at 165K, far above forecast.
Updated Sat 7 Nov 2026 · 01:52 GMT · New York closing prices Fri 6 Nov 2026 vs. close on Fri 30 Oct 2026
Key takeaways of the week
- 1Democrats won the US midterms and control both the House and the Senate. The dollar fell to a one-month low midweek, and gold broke above $4,000 and closed the week near $4,070, up about 5%
- 2October NFP rose 165K above the 65K forecast. Unemployment fell to 4.1% and average earnings rose 3.1% y/y. DXY jumped 0.77% on Friday, and markets price the odds of a Fed hike in December at about 78–80%
- 3Two central banks hiked rates: the RBA raised to 4.85% (6–3 vote) and the BoE raised to 4.00% (8–1 vote), its first hike in more than 3 years
- 4Tech stocks were sold off heavily on Thursday, with the Nasdaq down more than 5.5%. WTI crude fell almost 13% to around $90.8
Weekly performance
Closing prices Fri 6 Nov 2026 (New York) vs. close Fri 30 Oct 2026 · DXY: Investrade 102.32 / Trading Economics 102.28 / Reuters 102.26 · EUR/USD: Investrade 1.1142 / Reuters 1.1144 · GBP/USD: Reuters 1.3355 / Trading Economics 1.3355 · USD/JPY: Investrade 158.49 / Reuters 158.43 · Gold: Trading Economics $4,070 (+5.0%) / Investrade reports gold up 5.2% on the week · WTI: Investrade $90.83 / Trading Economics $90.34 (−13.2%) · US10Y: Investrade 4.855% / Trading Economics 4.867% · The Australian dollar is not shown because closing prices differed between sources · % rounded and may differ slightly by price source
What happened this week
The week opened with a sharp drop in oil after Iran signalled openness to talks, sending WTI crude below $98 on Monday 2 Nov, while the October ISM manufacturing index came in at 55.5, above the 54.7 forecast. On Tuesday 3 Nov the RBA raised rates by 0.25% to 4.85% on a 6–3 vote, as markets expected, before attention shifted to the US midterm elections that same night.
Results came in from Wednesday 4 Nov. Democrats took the House and then the Senate, the dollar fell to a one-month low, and gold surged about 3%, breaking above $4,000 to around $4,050. Eurozone inflation for October came in at 4.0% y/y, above forecast. Markets worried that the new Congress would be tougher on AI businesses, so the tech selloff intensified on Thursday 5 Nov, with the Nasdaq down more than 5.5%. The yen drew safe-haven demand. The same day the BoE raised rates by 0.25% to 4.00% on an 8–1 vote, with one member wanting a 0.50% hike.
On Friday 6 Nov the selling spread to Asia, where South Korea’s KOSPI plunged 8.55% and trading was briefly halted. That evening October NFP rose by 165,000 jobs, above the 65,000 forecast, with the previous two months revised up by a combined 84,000. DXY jumped 0.77% to around 102.26, its biggest one-day gain since mid-June. The US 10-year Treasury yield rose to around 4.85% but was still down about 7bp on the week. Gold eased about 0.9% on Friday yet still closed the week up about 5%, while WTI crude closed near $90.8, down almost 13% on the week.
Key data results of the week
- Mon 2 Nov · USHIGHISM manufacturing (Oct) 55.5 Above the 54.7 forecast; prices paid eased to 75.2 · Read analysis →
- Tue 3 Nov · AustraliaHIGHRBA hikes by 0.25% to 4.85% 6–3 vote, as expected · Read analysis →
- Wed 4 Nov · USDemocrats control both chambers Dollar at one-month low, gold up 3% · Read breaking news →
- Wed 4 Nov · EurozoneHIGHEurozone inflation (Oct) 4.0% y/y Above the 3.9% forecast; core inflation steady at 2.5% · Read analysis →
- Wed 4 Nov · USISM services (Oct) 54.5 Below the 54.7 forecast; new orders slowed to 55.9 · Read analysis →
- Thu 5 Nov · UKHIGHBoE hikes by 0.25% to 4.00% 8–1 vote, first hike in more than 3 years · Read analysis → · Central bank rates table →
- Fri 6 Nov · USHIGHNFP (Oct) 165K Above the 65K forecast; unemployment 4.1%, average earnings +0.4% m/m · Read analysis →
- Fri 6 Nov · USUMich consumer sentiment, preliminary (Nov) 51.0 Up from 48.0 previously; 1-year inflation expectations 4.3%
Daily gold: Gold price today →
Week ahead
The main theme next week is US inflation After a strong NFP, markets have added weight to the view that the Fed will hike another 0.25% at its 8–9 Dec meeting. October CPI is due on Tuesday 10 Nov at 13:30 GMT, with markets expecting +0.3% m/m, down from 0.6%. A hotter print could lift the dollar and yields further and weigh on gold, followed by PPI on Friday 13 Nov. See rates and the next meeting dates in the central bank rates table
Outside the US, watch Chinese inflation early Monday, UK Q3 GDP on Thursday and eurozone GDP on Friday. On Wednesday 11 Nov the US bond market is closed for Veterans Day, so liquidity may be thinner. Risks to watch are a return of tech-stock selling and Iran-talks headlines that keep oil volatile. This information is for education only and is not investment advice.
- China CPI inflation (Oct)Mon 9 Nov · Previous 0.9% y/y · Forecast 0.8%HIGH
- US CPI (Oct)Tue 10 Nov · Previous 0.6% m/m · Forecast 0.3%HIGH
- UK GDP Q3 (preliminary)Thu 12 Nov · Previous 0.5% q/qHIGH
- US PPI (Oct)Fri 13 Nov · Previous 1.3% m/m · Forecast 0.4%HIGH
Our view
The dollar is still supported by strong jobs data and the chance of a Fed hike in December, while gold is drawing demand from US political uncertainty and the tech selloff. The deciding event next week is CPI on Tuesday evening.
- 1CPI Tuesday 13:30 GMTA hotter-than-expected print tends to support the dollar and weigh on gold
- 2Gold near $4,000A psychological level that price only just reclaimed this week
- 3Use a stop loss on every tradeTech stocks and Iran headlines can flip markets between risk-on and risk-off quickly
Gold up 5% in US election week: get cash back on every lot
Rebate per lot · Standard Plus account
Rebate per lot · Standard account
Rebate per lot
1TRADER is a broker Partner (IB) and earns a commission when you open an account through our links · % is the share of the IB commission paid back to you, not a share of your deposit · Rates as of Sep 2026 · Compare rebates across brokers
Learn to trade free with 1TRADER
Sources (11)
- BLS – Employment Situation, October (6 Nov)
- Reuters via GV Wire – Dollar after NFP (6 Nov)
- Reuters via Yahoo Finance – Yields after NFP (6 Nov)
- Investrade – Market Review (6 Nov)
- Trading Economics – Currencies
- Trading Economics – Commodities
- Trading Economics – US10Y
- RBA – Monetary Policy Decision (3 Nov)
- Bank of England – Monetary Policy Summary, November 2026
- Investrade – Weekly calendar 9–13 Nov
- Newsquawk – Week Ahead 9–13 Nov
Risk warning: Trading Forex, gold and CFDs carries a high level of risk and you may lose all of your capital. This news is a summary for educational purposes, not investment advice. Prices in this article may have changed by the time you read it.
Compiled by the 1TRADER editorial teamEditorial and sourcing policyFull risk disclosure
Read more
Related news
 Forex NewsForex News 6 Nov 2026: Tech Stocks Slump, Gold Holds $4,087, BoE Hikes
 Forex NewsBreaking: Wall Street's Worst Day Since Apr 2025, Nasdaq −5.5%, Gold $4,100
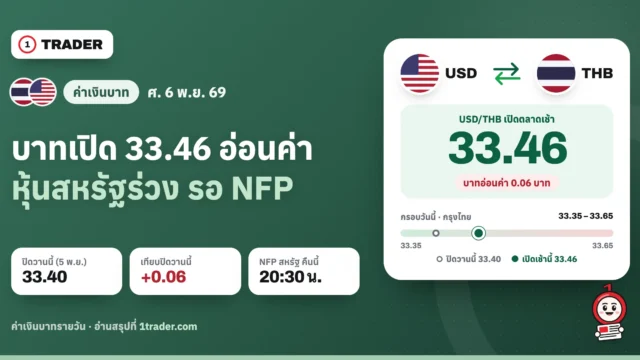 Forex NewsThai Baht Today 6 Nov 2026open 33.46 weaker as US stocks fall ahead of NFP tonight
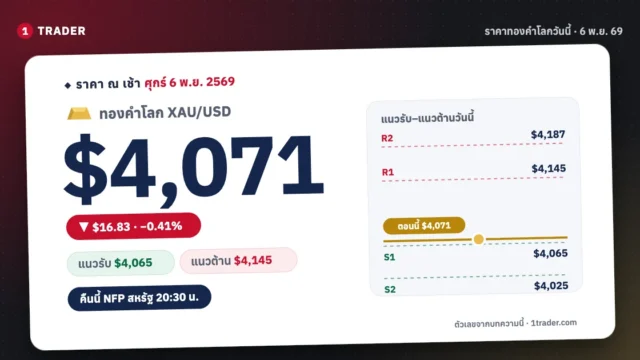 Forex NewsGold Price Today 6 Nov 2026: XAUUSD Near $4,071, Eases Ahead of NFP